
Choosing the Right Charitable Gifts for Your Estate Plan
Supporting a favorite charity can make a lasting difference. However, the way you give may affect both the charity’s benefit and your financial future. While cash donations are common, appreciated investments and retirement accounts may offer additional advantages. Choosing the right charitable gift depends on your financial circumstances, tax situation, and estate planning goals. Before making a significant donation, consider how each option works and whether it fits your long-term plans.
Giving Cash to Charity
Cash donations offer one of the simplest ways to support a charitable organization. You can write a check, make an online contribution, or establish recurring donations. In addition, many qualified charitable gifts may provide income tax benefits. However, not every payment to a charity qualifies for a full deduction. For example, purchasing a ticket to a fundraising dinner may include the value of your meal. Generally, only the amount exceeding the fair market value of what you receive qualifies as a charitable contribution.
Tax deductions also depend on current federal rules, your income, and whether you itemize deductions. Beginning in 2026, certain taxpayers who don’t itemize may qualify for a limited deduction for eligible cash contributions.
Because charitable deduction rules change, consult your tax advisor before assuming a contribution will reduce your taxes.
Donating Appreciated Stock or Property
Appreciated property includes assets that have increased in value since you purchased them. Common examples include stocks, mutual funds, and real estate. Instead of selling these assets and donating the proceeds, you may benefit from transferring them directly to a qualified charity.
This approach can offer several advantages:
- Avoiding capital gains tax: Donating qualifying appreciated property directly may allow you to avoid recognizing gains that would otherwise result from selling it.
- Increasing the charity’s benefit: An eligible tax-exempt organization may receive the asset’s full value without the capital gains tax that an individual seller might owe.
- Receiving a potential deduction: Depending on the asset and holding period, you may qualify for a charitable deduction based on its fair market value.
For example, suppose you purchased stock for $5,000, and it is now worth $15,000. Selling the stock could trigger capital gains taxes on the $10,000 increase. However, donating the shares directly may avoid that taxable sale.
Special rules apply to property donations, including holding periods, deduction limits, and appraisal requirements. Therefore, coordinate with your financial and tax advisors before transferring valuable assets.
Also, confirm that the organization accepts noncash contributions. Some smaller charities lack the resources to manage stock transfers or real estate donations.
Using Retirement Accounts for Charitable Giving
Retirement accounts offer another opportunity to support charitable organizations. Depending on your age and estate planning goals, you can make gifts during your lifetime or designate a charity as a beneficiary.
Qualified Charitable Distributions
If you are at least 70½, you may qualify to make a qualified charitable distribution (QCD) directly from an eligible IRA to a qualified charity.
A QCD can provide several benefits:
- The eligible distribution generally stays out of your taxable income.
- It can count toward your required minimum distribution (RMD) when applicable.
- The charity receives financial support without requiring you to withdraw and donate the money separately.
However, you cannot claim an additional charitable deduction for the same QCD. Annual limits and other eligibility requirements also apply. This strategy may appeal to retirees who want to support charitable causes while managing taxable retirement income.
Naming a Charity as a Retirement Account Beneficiary
You can also designate a qualified charity as a beneficiary of your IRA or other retirement account. When individuals inherit traditional retirement accounts, distributions generally create taxable income. In contrast, qualified tax-exempt charities usually don’t owe income tax on those distributions.
Consequently, leaving retirement assets to charity may preserve more of the account’s value for charitable purposes.
Meanwhile, other assets may be better suited for family members. For example, inherited assets that receive a favorable adjustment in tax basis may create different tax consequences than inherited retirement accounts.
Your estate planning attorney and tax advisor can help evaluate which assets to leave to loved ones and which to designate for charitable giving.
How Charitable Giving Fits Into Estate Planning
Charitable giving isn’t limited to immediate donations. You can also incorporate charitable goals into your estate plan through beneficiary designations, wills, or trusts. Depending on your circumstances, these arrangements may help you:
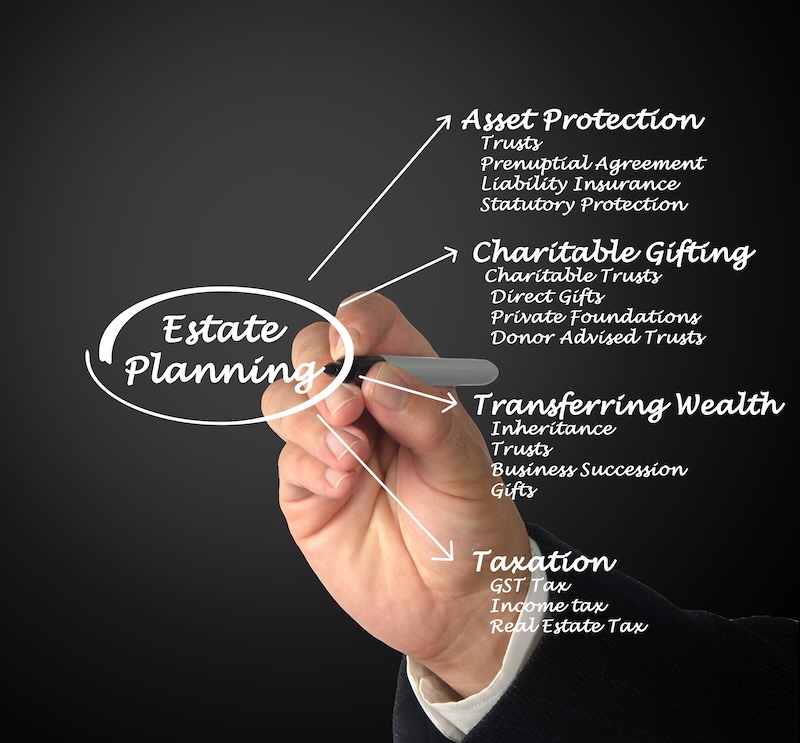
- Support organizations that reflect your values.
- Provide for family members while planning charitable gifts.
- Establish clear instructions for distributing assets.
- Potentially reduce estate taxes when applicable.
- Create a lasting legacy through planned giving.
However, charitable contributions shouldn’t compromise your own financial security. Before committing substantial assets, consider retirement expenses, healthcare needs, and family obligations.
Additionally, review charitable designations when your circumstances change. Marriage, divorce, retirement, or significant changes in your assets may affect your original plans.
Choosing the Best Charitable Giving Strategy
No single donation method works for everyone. Cash offers simplicity, appreciated property may provide capital gains advantages, and retirement accounts can create opportunities for tax-efficient giving.
The right approach depends on your assets, charitable intentions, and overall estate plan. Moreover, coordination among your attorney, financial advisor, and tax professional can help prevent unintended consequences.
At Skvarna Law Firm, we help clients consider charitable giving as part of their broader estate planning goals. Contact our office to discuss how thoughtful planning can support the people and organizations that matter most to you.
About Skvarna Law Firm in Glendora and Upland, California
Skvarna Law Firm operates offices in Glendora and Upland, California. We provide legal services. We cover San Bernardino, Los Angeles, Orange, and Riverside Counties. This includes several cities. Upland, Ontario, Rancho Cucamonga, Fontana, Colton, Rialto, Chino, Chino Hills, Glendora, Claremont, Pomona, La Verne, Montclair, San Dimas, Azusa, Covina, West Covina, Diamond Bar, Walnut, La Puente, Corona, Norco & Mira Loma. Visit SkvarnaLaw.com to learn more.
